Your mortgage.
More options.
Better strategy.
We don't just find you a mortgage. We build a financing strategy around your goals, your life, and what's next.
Ready now? Apply online or text us — your pace, your call.
The right loan is the one built for your situation.
Because we're independent, we shop multiple lenders and programs. Start with the one that sounds like you — every tile opens a full program page.
Conventional
Flexible terms for strong credit and down payments as low as 3%.
FHA
Lower down payment and more forgiving credit guidelines for first-time buyers.
VA
Zero-down financing for veterans, active duty, and eligible surviving spouses.
Jumbo
Loan amounts above conforming limits for higher-value Arizona & Utah homes.
Self-Employed / Non-QM
Bank statement, P&L, and asset-based options when tax returns don't tell the story.
Investor / DSCR
Qualify on the property's rental income, not your personal DTI.
Construction
Build-to-permanent financing from ground break to move-in.
Hard Money
Fast, asset-backed capital for flips, bridges, and time-sensitive deals.
Down Payment Assistance
Arizona and Utah programs that can cover part or all of your down payment.
Business Purpose
Commercial, SBA, and business-purpose lending for owners and operators.
Local expertise. More lending options.
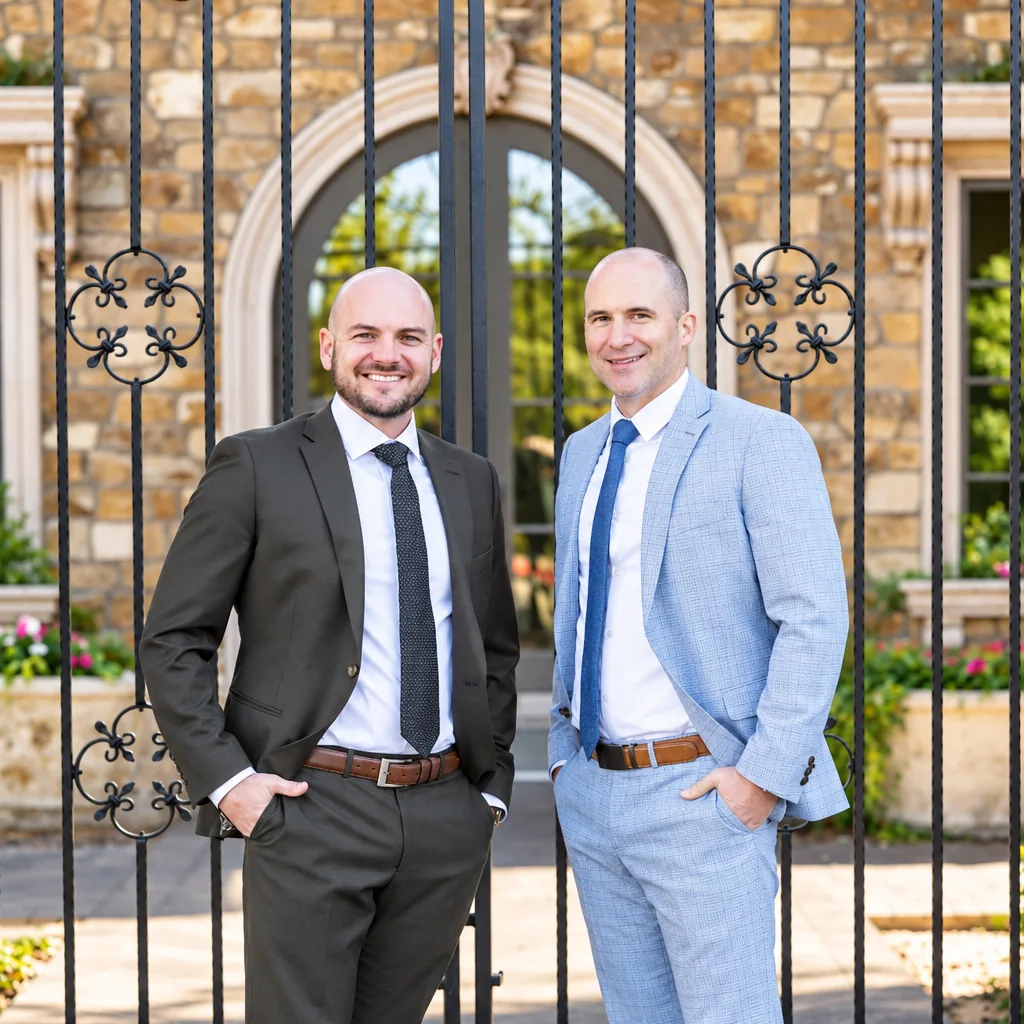
The Mortgage Collective is an independent mortgage brokerage based in Mesa, Arizona, helping homebuyers, homeowners, and real estate investors find smarter financing solutions throughout Arizona, Utah, and other states we serve. With more than 50 years of combined mortgage experience, our team shops multiple lenders and loan programs to help you find competitive rates, flexible options, and a mortgage strategy built around your goals.
Whether you're buying a home, refinancing, accessing equity with a HELOC, financing an investment property, or looking for a more specialized mortgage solution, we're here to make the process personal, strategic, and straightforward. We're not just here to close your loan — we're here to become the mortgage team you trust for years to come.
Meet the team →We built the Collective because there was a better way to do mortgages.
You choose a broker, not a brokerage. Here's who picks up when you text.
Not a loan number.
Part of the Collective.
Every review here is quoted word for word from Google. Names and dates are as posted.
Why choose The Mortgage Collective over other lending options?
A big bank sells you its loan. An online lender sells you its algorithm. We work for you, and we shop everyone.
| The Mortgage Collective | Online Lenders | Retail Banks | |
|---|---|---|---|
| Shops multiple lenders for your rate | ✓ | ✕ | ✕ |
| Wide program menu (Non-QM, DSCR, DPA, construction) | ✓ | Limited | Limited |
| A strategy built around your goals, not a product | ✓ | ✕ | ✕ |
| One local advisor start to finish | ✓ | Call center | Rotating staff |
| Local Arizona & Utah market knowledge | ✓ | ✕ | Varies |
| Reachable after hours, by text | ✓ | ✕ | ✕ |
| Transparent about how we're paid | ✓ | Buried | Buried |
| A relationship that outlasts the closing | ✓ | ✕ | Sometimes |
Where rates are right now.
These are national averages from Mortgage News Daily, updated every business day from real lender rate sheets, with Freddie Mac's weekly survey below them. They're a market snapshot, not a quote. Your rate depends on your credit, down payment, property, and loan program.
As a broker we compare pricing across many wholesale lenders at once to find the right fit for your situation.
Buyer math, before the sales pitch.
Three quick calculators to size up a payment, a price range, and whether owning beats renting. Estimates only — a strategy call turns them into real numbers.
Assumes taxes, insurance, and mortgage insurance at about 1.6% of price per year. Programs like FHA and DPA can change this range — that's what the strategy call is for.
Not sure where you land? Take the 60-second "Can I buy?" check — four questions, no credit pull, and you'll see which programs likely fit.
Pick the door that suits you. We'll meet you there.
Text us now
Fastest way in. Start a text conversation and we'll schedule a call around your day.
Replies within business hours Start TextingSchedule a call
A 30-minute Strategy Pre-Approval Call. Bring your goals; we'll bring the options.
Pick a time that works Book on Our CalendarApply now
Ready to go? The secure application takes about ten minutes, and we'll follow up the same day.
Secure · ~10 minutes Start ApplicationOr take the quick "Can I buy?" check first — it's four questions and tells you which programs likely fit before we ever talk.
Market notes, buyer math & straight answers.
How Much House Can You Afford in the East Valley Right Now?
Affordability isn't just about the price tag—it's about understanding what you can comfortably carry each month.
First-Time BuyersPre-qualified vs. pre-approved: what Gilbert sellers actually look for
The two words get used interchangeably. In a competitive East Valley offer, only one of them carries weight.
Questions we hear before the first call.
Don't see yours? Text us — it's usually a two-minute answer.
What's the difference between a broker and a bank?
A bank can only offer its own loans. As an independent brokerage, we have access to dozens of wholesale lenders and can place your loan where the rate, guidelines, and timeline fit you best.
How do you get paid?
Plainly: on most loans we're paid by the wholesale lender at closing, and that compensation is disclosed on your Loan Estimate and Closing Disclosure. On some loans you can choose to pay us directly instead, which can lower your rate. Either way, you'll see the number in writing before you commit — no surprises.
How much do I need for a down payment?
Often less than you think. Conventional loans start at 3% down, FHA at 3.5%, VA at 0%, and Arizona and Utah down payment assistance programs can cover part or all of it. We'll map the options to your cash on hand.
I'm self-employed. Can I still qualify?
Yes. Beyond standard tax-return underwriting, we offer bank statement, P&L, and asset-based programs designed for business owners whose returns understate their real income.
What is a pre-qualification vs. a pre-approval?
Pre-qualification is a quick estimate of what you can afford. A pre-approval means we've verified income, assets, and credit — it's the letter that makes your offer competitive. We do both, starting with a short strategy call.
How fast can we close?
Most purchase loans close in 21–30 days. Hard money and certain DSCR programs can move faster when a deadline demands it.